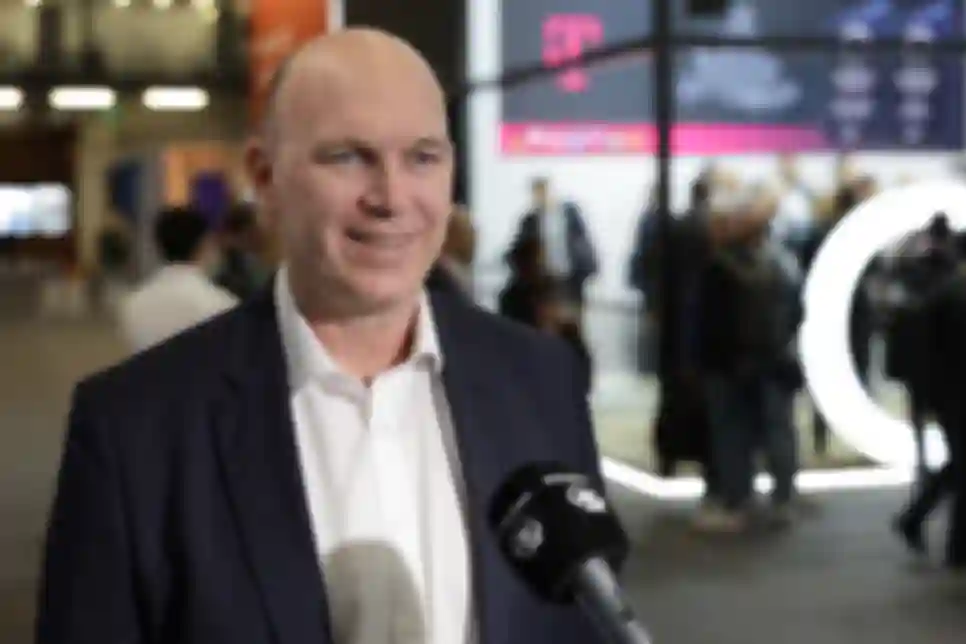
Croatia’s telecom market has significantly accelerated investment in fiber and mobile infrastructure after a period in which fiber deployment lagged behind market needs. Competition between operators, EU funding and commercial investment have changed the pace of network rollout, while 5G is already delivering substantial capacity and speeds in larger population centres. “We really were behind on fiber infrastructure, but the market has moved, and competition has intensified,” Adrian Ježina, CEO of Telemach Croatia, tells ICTbusiness Media - ICTbusiness.info. In his view, the priority now is to use the current momentum to bring fiber coverage as close as possible to nationwide coverage.
Ježina distinguishes between commercially attractive areas, where operators can continue investing on their own, and rural areas where public support remains important. High-quality digital connectivity, he argues, should increasingly be treated as essential infrastructure, much like electricity and water. “It would be a shame not to use this momentum to reach, if possible, one hundred percent of Croatia,” he says, adding that deployment is a long-term process and that reducing administrative barriers could make construction faster.
The mobile market is in a different position because 5G is already widely present. All three operators have network capacity and coverage in larger population centres, and Ježina believes Croatia is performing well in this respect. “Infrastructure investment is substantial, and I believe Telemach and the other companies will continue investing so that we remain aligned with global trends,” he says. Infrastructure, however, is only one part of this market transformation.
Telecom operators no longer compete only with each other. Global platforms have changed traditional communications, from messaging applications that have displaced a significant share of SMS traffic to streaming services that have transformed television. Local operators therefore compete with companies operating globally and setting high standards for user experience. “That forces us and our services to become better,” Ježina says.
One response is the development of platforms that bring local and global content together. “The goal is for these platforms to become a kind of one-stop shop, with all the local content and the global services users want to watch,” he explains. He expects such services to remain relevant because local operators understand their markets and customers, while still having to match the experience delivered by international platforms.
Ježina also points to an imbalance between operators that invest in networks and global digital services that use those networks to deliver their products. He does not expect the competitive structure to change quickly. “If everyone uses the same or similar technology, the order largely remains the same; the question is whether someone can create something truly revolutionary,” he says. Technologies such as 5G Advanced and, later, 6G may open new opportunities, but commercial impact will not follow simply because a new generation of network technology exists.
The experience with 5G illustrates the point. The technology brought more capacity, lower latency and the ability to connect far more devices, yet smaller markets with a limited industrial base cannot immediately generate enough large-scale use cases. “Technology often has to arrive first, and services are then developed on top of it,” Ježina says, drawing a parallel with 4G, which created the conditions for the rapid expansion of streaming, cloud services and social platforms.
Private networks and differentiated quality of service are therefore likely to emerge gradually, particularly where there is a concrete need for priority, reliability or guaranteed capacity. Croatia may adopt such models more slowly than large industrial economies, with some solutions first maturing in larger markets before being adapted to local scale.
Technology will not be the only force shaping the sector. Ježina highlights labour availability and cost, productivity, energy, inflation, the investment climate and the state’s ability to accelerate digitalisation. “A country needs to develop infrastructure, but also research and development,” he says, arguing that investment incentives and simpler infrastructure deployment should have a stronger role than additional burdens.
The third layer is European regulation, from cybersecurity to digital markets. Ježina does not prejudge its final impact because new rules can affect prices, investment speed and competitiveness in different ways. The future of telecoms will therefore be shaped by several processes at once: continued infrastructure investment, the development of services on top of new networks, the relationship with global platforms, and the regulatory and economic environment in which operators must continue to invest.